

Most people don’t wake up one morning wanting to rethink their health insurance. Usually, something happens first.
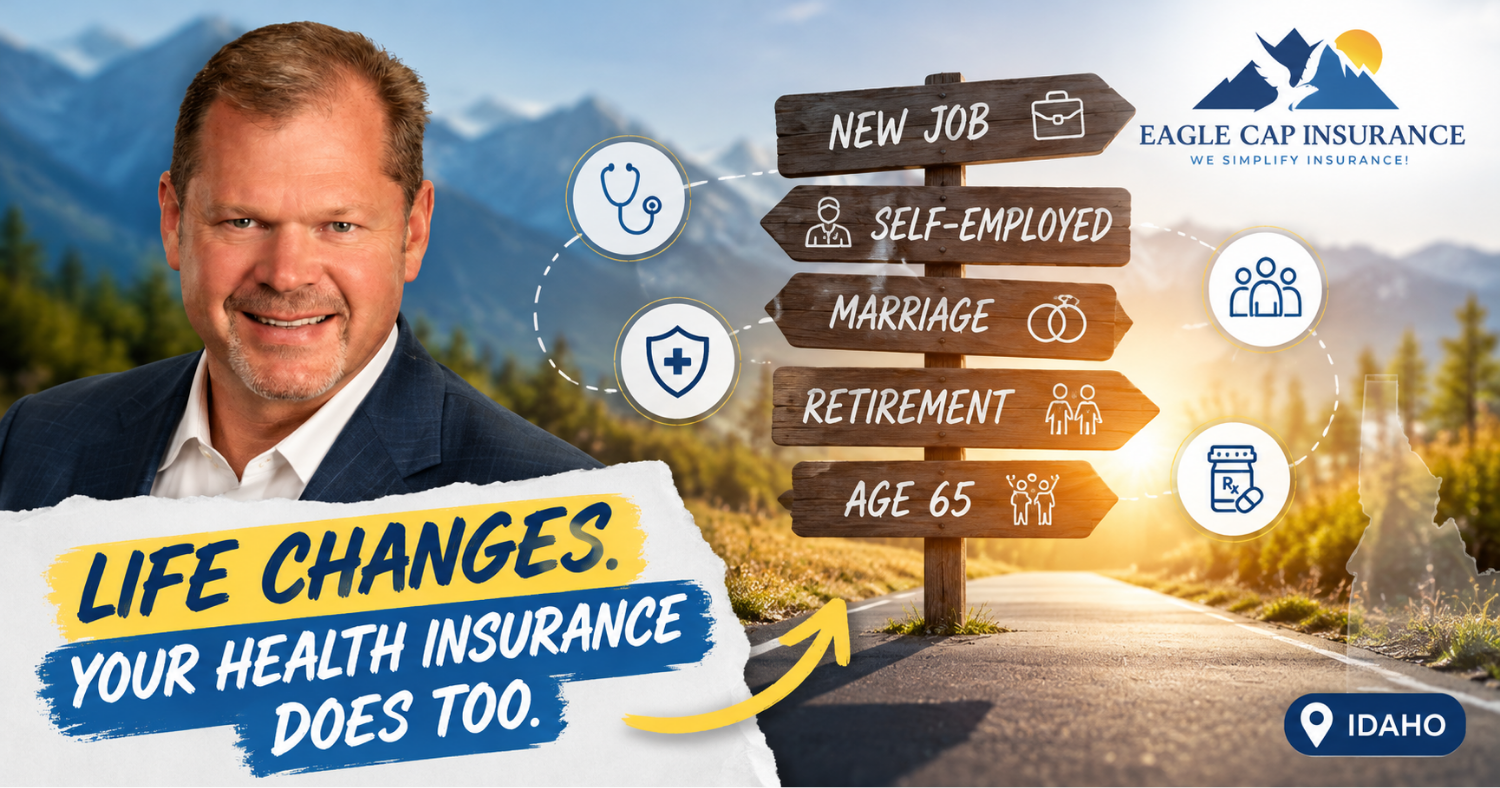
You leave a job. Start working for yourself. Get married or divorced. A child turns 26. You move. You retire. You reach an age when the way your healthcare coverage works begins to change.
These transitions matter because the health insurance arrangement that worked during one stage of life may not work the same way in the next. Your eligibility can change. The contribution your employer used to make can disappear. Your household income may look different. New enrollment rules can apply, and the doctors, hospitals, prescriptions, deductibles, and financial assistance attached to your available options may change too.
That is why Kyle Bennett of Eagle Cap Insurance approaches major insurance transitions differently. Before getting into insurance companies and individual plans, he starts with education. What coverage are you leaving? What system are you moving into? What choices will you have, and what differences actually matter to you?
That process is at the center of the video in this guide.
Watch Kyle: Why Education Comes Before Choosing Coverage
Kyle uses people approaching age 65 as the example in this conversation. His process begins with an educational overview before moving into specific private insurance options. He explains the basic pieces of the federal health coverage system, the ways private insurance can interact with it, and the tradeoffs that can affect someone’s decision.
One number from the conversation is worth correcting for context. Kyle mentions more than 12,000 people turning 65 every month. The demographic shift is actually much larger. Recent congressional material describes the ongoing “Peak 65” period as more than 4.1 million Americans reaching age 65 each year through 2027, or more than 11,200 every day.
But the demographic statistic isn’t the most useful part of Kyle’s discussion. His process is.
Whether someone is turning 65, losing employer coverage at 45, or becoming self-employed at 35, there is a valuable rule behind it:
Learn how your new coverage situation works before you start comparing plans.
The Coverage Transition Playbook
A major life event shouldn’t immediately trigger a search for the cheapest insurance policy. First, identify what the event actually changes.
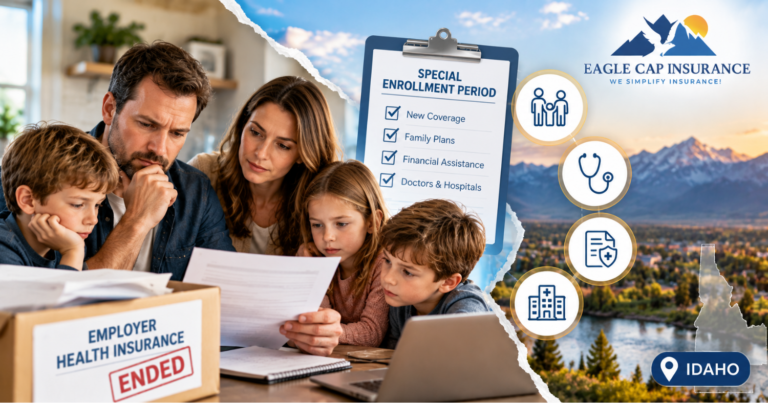
In Idaho, for example, losing employer-sponsored health coverage can create a Special Enrollment Period through Your Health Idaho. Loss of employer or a spouse’s employer coverage, exhaustion of COBRA, aging out of a parent’s plan at 26, and certain other losses of qualifying coverage can create a 60-day enrollment opportunity. Loss of Medicaid or CHIP can provide a 90-day window. Verification of the qualifying event is required.
That means the same question, “What health insurance should I get?”, can have very different answers depending on why someone is asking it.
| Life change | What can change with your insurance | What should be reviewed first |
| Leaving a job | Employer coverage and employer premium contributions may end | Coverage termination date, Special Enrollment eligibility, COBRA and individual coverage |
| Becoming self-employed | You may need to arrange coverage independently | Household income, Marketplace eligibility, network and total cost |
| Marriage or divorce | Household composition and available coverage can change | Enrollment rights, dependents, income and access to employer coverage |
| Child turns 26 | Eligibility under a parent’s plan generally ends | Coverage-end date and Special Enrollment options |
| Moving | Plan availability and provider networks may change | New service area, doctors, hospitals and enrollment eligibility |
| Retirement | Employer coverage may end or coordinate differently | Age, spouse coverage, retiree benefits and applicable federal coverage |
| Approaching 65 | A different health-coverage system becomes relevant for many people | Enrollment timing, existing employer coverage and available coverage structures |
The objective at this stage isn’t to choose an insurance company. It is to build a map of what coverage is actually available.
When the System Changes, Learn the System Before the Product
This is where Kyle’s age-65 example becomes useful without turning the entire conversation into one about Medicare.
Someone who has spent decades receiving health insurance through an employer may suddenly encounter unfamiliar terminology and coverage structures. In the federal system Kyle discusses, Part A generally provides hospital insurance and Part B medical insurance. Once enrolled in Parts A and B, there are two main ways to receive that coverage: Original Medicare or a Medicare-approved private Medicare Advantage plan. Someone using Original Medicare can also potentially add separate prescription drug coverage and private supplemental insurance.
Kyle’s educational approach is to explain those structures before asking someone to choose between them. That’s important because they do not function identically.
For example, Original Medicare generally allows a beneficiary to use any doctor or hospital that accepts Medicare anywhere in the United States. Private Medicare Advantage plans may require non-emergency care to be obtained from providers within the plan’s network and service area, although some plans provide out-of-network coverage at additional cost. Prior-authorization requirements can also differ.
Kyle also references supplemental Plan G and Plan N coverage. Medicare confirms that Medigap policies are standardized, meaning policies with the same letter provide the same standardized benefits even when sold by different insurance companies. Premiums and other carrier considerations can still vary.
Those details are relevant to the particular transition Kyle is discussing. The larger lesson applies to virtually every health-insurance transition: don’t compare products until you understand how the underlying coverage works.
Your Insurance Company Isn’t the First Thing to Compare
Once the available coverage paths are clear, the conversation can move from eligibility to fit.
Start with your healthcare rather than an insurance-company logo. Which doctors do you want to keep? Do you regularly see specialists? Which hospitals would you prefer to use? What prescriptions do you take? Are there procedures or treatments you already know you will need? How frequently does your family typically use healthcare?
Then bring the financial side into the same conversation. A $0 or low monthly premium doesn’t tell you the deductible, copays, coinsurance, prescription costs, provider access, or total financial exposure you could face during a high-use year.
A useful insurance comparison therefore looks more like this:
| Review area | What you’re trying to find out |
| Eligibility | Which coverage choices are actually available after this life change? |
| Effective date | When does the old coverage stop and the new coverage begin? |
| Monthly premium | What does maintaining the coverage cost? |
| Deductible and cost sharing | What might you pay when you actually use healthcare? |
| Maximum exposure | What financial protection does the plan provide during a high-cost year? |
| Doctors and hospitals | Are the providers that matter to you accessible under the coverage? |
| Prescriptions | Are your medications covered, and under what cost-sharing rules? |
| Financial assistance | Are Marketplace tax credits or other assistance available? |
| Future flexibility | What happens if employment, income, residence or healthcare needs change again? |
This is why health insurance decisions can go wrong when the premium becomes the entire conversation. The premium matters, but it is one variable inside a much larger financial and healthcare decision.
Idaho’s Individual Health Insurance Market Makes Comparison Even More Important
For Idaho residents leaving employer coverage or otherwise entering the individual market, there are substantial choices to evaluate.
For 2026, the Idaho Department of Insurance reported eight carriers offering individual health coverage and 158 medical plans available through Your Health Idaho. The Department also reported that individual-market premiums increased by an average of 10% for 2026.
Those numbers don’t mean one Idaho consumer actually has 158 reasonable options. Plan availability varies, and someone’s practical choices become much narrower after accounting for location, eligibility, household circumstances, provider networks, prescriptions, expected healthcare use and budget.
The Idaho market also illustrates why understanding insurance mechanics matters. The state’s Section 1332 reinsurance waiver offsets some of the premium impact associated with high-cost health conditions. The Idaho Department of Insurance estimated that the waiver made 2026 individual-market premiums approximately 18% lower than they otherwise would have been without the program.
There is another important distinction for people shopping on their own: financial assistance through the state Marketplace can materially affect what coverage costs. Your Health Idaho allows eligible consumers to determine whether they qualify for tax credits and other savings when enrolling.
This is why moving from an employer plan into individual coverage shouldn’t simply become a search for “cheap health insurance in Idaho.” The structure of the market, household eligibility and actual healthcare needs all influence the decision.
What If You’re Retiring but Aren’t 65 Yet?
This is one of the most practical gaps in the health-insurance conversation.
Retirement and health-coverage eligibility do not necessarily begin at the same time. Someone who retires before becoming eligible for the federal coverage Kyle discusses still needs a strategy for the period between employer coverage ending and the next coverage stage beginning.
Depending on the circumstances, that may involve COBRA, coverage through a spouse’s employer, or individual coverage. Losing employer-sponsored insurance may also create a Special Enrollment Period through Your Health Idaho.
This is a good example of why the timeline matters as much as the plan. Someone retiring at 62 has a different coverage problem from someone retiring after 65 while covered by a large employer. The right starting question is not simply “What retirement health insurance should I buy?” It is “What coverage am I losing, when does it end, and what becomes available to me next?”
What If You’re Becoming Self-Employed?
Leaving a traditional job to start a business creates another transition that can fundamentally change the health-insurance equation.
The employer may previously have paid part of the premium, administered enrollment and offered a relatively small set of plans. Once self-employed, the individual may become responsible for navigating coverage independently.
That makes expected household income particularly important when evaluating Marketplace coverage because eligibility for financial assistance depends on applicable household and income rules. Provider networks and total cost also become important because the cheapest premium may not produce the lowest overall healthcare spending for someone who regularly uses medical services.
For an Idaho contractor, consultant, farmer, chiropractor, small-business owner or other self-employed professional, health insurance also becomes part of a broader protection conversation. Health insurance addresses eligible healthcare expenses. It does not replace income when illness or injury prevents someone from working, which is why disability coverage can become a separate consideration for people whose livelihood depends heavily on their own ability to work.
Build Your Personal Coverage File Before You Compare Anything
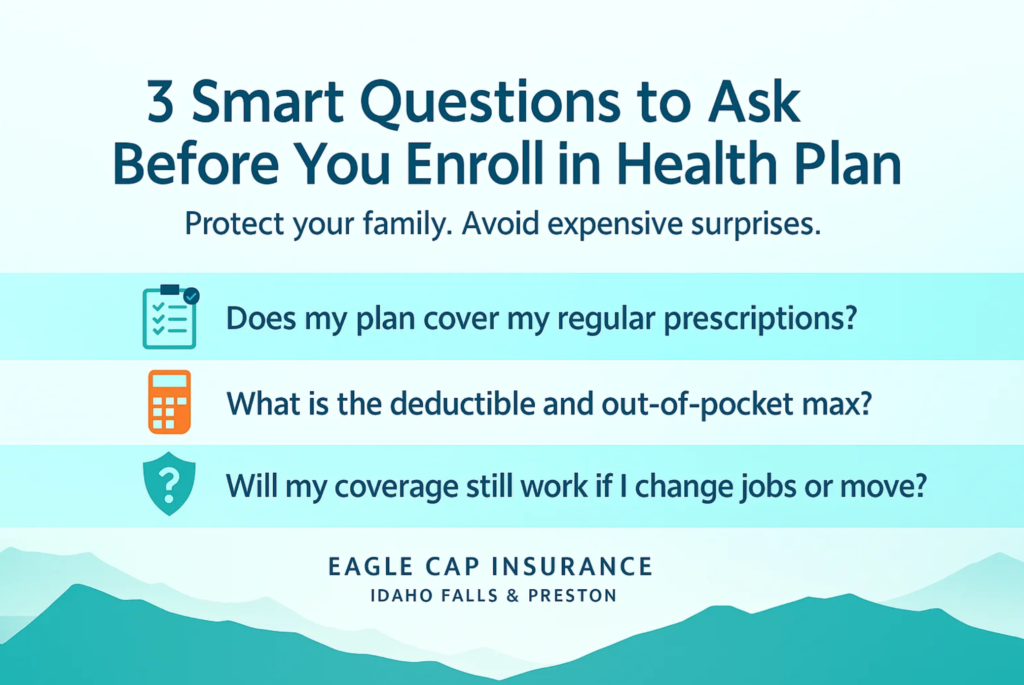
A productive insurance review becomes much easier when the information is already in front of you. Before meeting with an advisor or comparing plans, gather the end date of your existing coverage, information about household members who need insurance, expected household income, current doctors and specialists, preferred hospitals, prescription names and dosages, expected procedures or ongoing treatment, and information about any employer, spouse, retiree or other coverage available to you.
Then identify the coverage paths for which you may actually be eligible. Only after that should you start narrowing individual policies.
This order prevents an extremely common problem: spending time comparing a plan that doesn’t fit your doctors, doesn’t fit your prescriptions, doesn’t fit the household’s eligibility situation, or doesn’t solve the coverage gap created by the life event in the first place.
Where Eagle Cap Insurance Fits Into the Process
The strongest point in Kyle’s video isn’t a statement about one particular insurance product. It is the way he describes his role.
Education comes first.
For someone approaching a new stage of health coverage, that means understanding what is changing before deciding what to purchase. For someone losing employer insurance, it may involve Special Enrollment rules, Marketplace eligibility and individual health plans. For someone becoming self-employed, household income and financial assistance may become part of the discussion. For someone approaching 65 or retirement, employer coverage and federal coverage can introduce a completely different set of considerations.
Eagle Cap Insurance helps individuals and families in Idaho Falls, Preston and surrounding Idaho communities work through those decisions by identifying the coverage transition, explaining the available insurance structures and helping clients compare how the options fit their healthcare needs.
The goal isn’t to make every client choose the same type of coverage. It is to help each client understand what they’re choosing.
When Life Changes, Put Your Health Insurance Back on the Table
Health insurance is easy to leave on autopilot when life stays relatively stable. Major transitions are when it deserves another look.
A new career can change where coverage comes from. Self-employment can change who pays for it. Marriage or divorce can change the household. Moving can change available networks. Retirement can end employer coverage. Reaching 65 can introduce an entirely different health-coverage system.
The insurance decision should change when the facts behind the decision change.
That is the practical lesson behind Kyle’s video. You don’t need to become an insurance expert before every major life event. You do need to understand what is changing, which coverage options are available, and what each option would actually mean for the way you receive and pay for healthcare.
Your health insurance shouldn’t simply follow you from one stage of life to another without being reviewed. When life changes, put the coverage back on the table and make sure it still fits.
Eagle Cap Insurance helps Idaho individuals and families understand their health insurance options and navigate coverage changes with an education-first approach.
Schedule a conversation with Kyle Bennett:
Book an appointment with Eagle Cap Insurance
Call Eagle Cap Insurance: 208-529-1522
Learn more about health insurance from Eagle Cap Insurance
Official Sources
Idaho Department of Insurance — 2026 Health Insurance Rates
Idaho Department of Insurance — Idaho Health Insurance Rate Review
Your Health Idaho — Loss of Coverage & Special Enrollment
Medicare.gov — Coverage Options
Medicare.gov — Comparing Original Medicare and Private Plan Coverage
Medicare.gov — Supplemental Coverage Basics
Disclaimer: This article is for general educational purposes only and does not provide individualized insurance, financial, legal, tax or medical advice. Health insurance eligibility, enrollment periods, financial assistance, premiums, benefits, provider networks, formularies, cost-sharing and plan availability depend on individual circumstances, location and applicable rules. Federal health-program information is included only as context for the life-stage transition discussed in Kyle Bennett’s video. Always verify current eligibility and coverage details before enrolling in or changing insurance.