

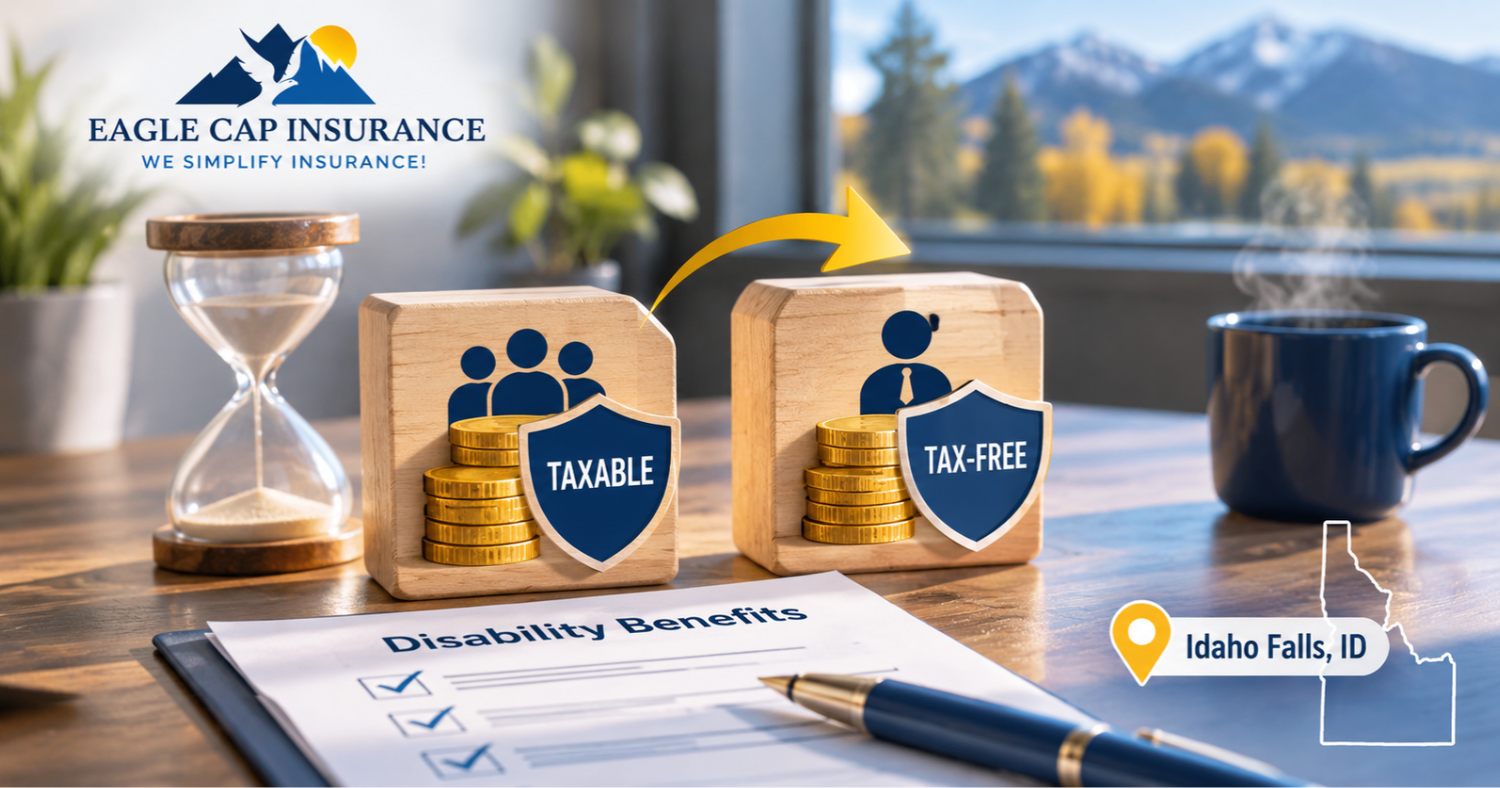
Imagine receiving $10,000 every month from a long-term disability insurance policy, only to discover that part of that money will go toward income taxes.
Now imagine receiving $5,000 from another disability policy, with the entire benefit generally excluded from federal taxable income.
Which policy would you rather have?
The answer depends on more than the monthly benefit. It depends on how the coverage was purchased, who paid the premiums, and whether those payments were made before or after taxes.
For healthcare professionals, business owners, and employees in Idaho Falls, understanding this distinction can make a meaningful difference when evaluating disability income protection.
Kyle Bennett of Eagle Cap Insurance shares a client experience that illustrates why the details matter.
Watch Kyle Bennett: Why One Disability Insurance Benefit Was Taxable and the Other Wasn’t
In this video, Kyle Bennett, founder of Eagle Cap Insurance, discusses a client who had two disability insurance policies: one purchased individually and another obtained through his employer.
The client eventually became unable to work because of health conditions. Both policies provided benefits, but the payments received different tax treatment.
Kyle explains why the employer-sponsored benefit was taxable while the individually purchased policy provided benefits that were not subject to federal income tax.
The lesson is particularly useful for professionals who already have disability insurance through work and assume that their employer-sponsored coverage will provide everything they need.
The Client Who Had Two Disability Insurance Policies
When Kyle began working with this client, the individual had lost his previous disability insurance coverage.
Kyle helped him explore individual disability insurance options. However, the client had existing health conditions that limited what insurers were willing to offer.
According to Kyle, they were able to obtain a personal disability policy providing $5,000 per month for a five-year benefit period.
The client also worked at a hospital, where he obtained employer-sponsored group disability insurance providing approximately $10,000 per month, with benefits potentially continuing until age 65 under that plan’s terms.
Eventually, the health problems Kyle had discussed became serious enough that the client went on long-term disability.
Both policies became important sources of income.
| Coverage Detail | Individual Disability Policy | Employer Group Disability Policy |
| Monthly benefit in Kyle’s example | $5,000 | $10,000 |
| Benefit period | Five years | Potentially until age 65 |
| Coverage source | Individually purchased | Hospital employer plan |
| Premium funding described | Client-paid | Employer-funded or subsidized |
| Federal income-tax treatment described | Benefits excluded from taxable income | Benefits taxable |
| Primary advantage | Additional income with favorable tax treatment | Larger benefit obtained through workplace coverage |
These amounts and circumstances come from Kyle’s client story. They are not typical benefit amounts or guarantees of coverage.
What makes this example interesting is that the client was frustrated about paying taxes on the larger group benefit.
Kyle saw the situation differently.
The employer had provided or substantially subsidized valuable coverage. Even after accounting for taxes, the client still had access to an additional source of disability income that might otherwise have been unavailable or expensive to obtain independently.
The two policies served different purposes, and together they provided more protection than either one alone.
Are Long-Term Disability Insurance Benefits Taxable?
Yes, long-term disability insurance benefits can be taxable, but the answer depends primarily on how the premiums were funded.
The Internal Revenue Service explains that disability benefits received under an employer-paid accident or health insurance plan generally must be reported as income.
When an individual pays the entire premium using after-tax dollars, benefits received for a covered disability are generally excluded from federal taxable income.
When the employer and employee share the premium cost, only the portion of benefits attributable to employer-paid premiums is generally taxable if the employee paid their share with after-tax dollars.
There is another important distinction: premiums paid through a workplace cafeteria plan using pre-tax dollars generally result in taxable disability benefits.
These rules are explained in the IRS’s official disability insurance tax guidance and Publication 525, Taxable and Nontaxable Income.
How Premium Payments Affect Disability Insurance Taxes
| How the Disability Insurance Premium Is Paid | General Federal Tax Treatment of Benefits |
| Employer pays 100% of premiums, and the premium cost is excluded from employee income | Generally taxable |
| Employee pays 100% using after-tax income | Generally not taxable |
| Employer and employee share premiums, with the employee paying after-tax | Generally taxable in proportion to employer funding |
| Employee pays through pre-tax payroll deductions | Generally taxable |
| Employee pays through payroll deductions using after-tax income | Generally not taxable if the employee funds the entire premium |
The key question is how the premiums were treated for tax purposes, not simply whether the policy was labeled “group” or “individual.”
A group policy funded entirely through after-tax employee contributions can provide benefits that are generally excluded from federal taxable income.
Likewise, the tax treatment of an individually owned policy can require additional review when premiums are paid through a business or deducted under particular arrangements.
Idaho residents should also consider applicable state income-tax treatment with a qualified tax professional.
Why Employer-Sponsored Disability Insurance Is Still Valuable
Kyle makes an important point in his video: the client was receiving a substantial monthly benefit through coverage his employer had provided or subsidized.
That benefit had real financial value.
Employer-sponsored disability insurance can give employees access to coverage at a group rate, with the employer sometimes paying part or all of the premiums.
It can also provide protection to workers who might otherwise have difficulty obtaining comparable individual coverage because of health conditions.
However, access to workplace disability insurance is far from universal.
According to the U.S. Bureau of Labor Statistics, 37% of private-industry workers had access to long-term disability insurance in March 2026. That is a national figure, not an Idaho-specific estimate.
For employees who do have access, understanding the plan’s benefits, exclusions, tax treatment, and continuation rules is an important part of reviewing their overall compensation package.
For employers, disability insurance can also be a meaningful component of an employee benefits strategy.
Why Healthcare Professionals and Business Owners May Need Both Policies
The client in Kyle’s video worked at a hospital, making his situation especially relevant to Idaho Falls healthcare professionals.
Physicians, nurses, therapists, administrators, and other healthcare employees may receive disability coverage through their employers. Some also purchase individual policies to supplement that protection.
There are several reasons to consider both.
An employer’s group plan may provide a valuable foundation, but its benefit limits, definition of disability, offsets, and continuation provisions may differ from those of an individual policy.
Individual disability insurance may provide additional income protection, subject to underwriting and the insurer’s rules regarding other existing coverage.
For business owners and self-employed professionals, the question is slightly different. They may have no employer-sponsored disability coverage at all.
That makes personally owned disability income insurance especially relevant when household expenses depend on income generated through the owner’s work.
The Idaho Department of Insurance recommends reviewing disability insurance coverage amounts, waiting periods, benefit periods, and exclusions before purchasing a policy.
Those features matter just as much as the monthly premium.
Can You Receive Benefits From Group and Individual Disability Insurance at the Same Time?
Potentially, yes. Kyle’s client story illustrates a situation in which both policies paid benefits.
However, receiving payments from two disability insurance policies is not guaranteed simply because both policies exist.
Each policy has its own eligibility requirements, definition of disability, benefit limits, and provisions addressing other income or benefits.
Some disability policies reduce payments when the insured receives income from specified other sources. Others have different coordination provisions.
The State of Idaho Office of Group Insurance notes that disability benefits under its program may be reduced by other sources of income. This illustrates why coordination provisions must be checked, although the rules of that state employee plan do not apply automatically to private hospital plans or individual policies.
Before relying on two policies to provide a combined benefit, the insured should understand how they interact.
That review becomes particularly important when one policy has a shorter benefit period than the other.
In Kyle’s example, the individual policy had a five-year benefit period, while the group policy potentially continued until age 65.
Those different durations could significantly affect the client’s income over time.
How Eagle Cap Insurance Helps Idaho Professionals Understand Their Disability Coverage
This is where working with an experienced insurance advisor becomes valuable.
A disability insurance review involves more than comparing premium quotes.
Kyle Bennett and Eagle Cap Insurance help Idaho residents understand the coverage available to them and how different policies may fit together.
For someone who already has employer-sponsored disability insurance, Kyle can help review the policy’s monthly benefit, waiting period, benefit duration, disability definition, and relevant exclusions.
He can also help evaluate whether individual disability insurance may provide additional protection.
For professionals with existing health conditions, the application process may require particular attention because medical underwriting can affect eligibility, available benefits, exclusions, and pricing.
Kyle’s client story demonstrates that process. Although the client could not obtain the full amount or duration of individual coverage originally desired, Kyle helped him secure an available policy that later provided an additional source of income.
Eagle Cap can also help clients identify questions about premium funding and potential tax treatment that should be reviewed with their employer’s benefits administrator, payroll department, or tax professional.
The IRS determines the applicable tax rules. An insurance advisor can help explain policy provisions and coordinate the insurance review, but should not replace individualized tax advice.
For clients in Idaho Falls, Ammon, Preston, and surrounding Idaho communities, these conversations can also begin remotely when reviewing existing coverage or exploring available individual disability insurance options.
The Real Lesson From Kyle’s Client Story
The client in Kyle’s video had two policies with different benefits, different durations, and different tax consequences.
The $10,000 employer-sponsored benefit was taxable. The $5,000 personally funded benefit was generally excluded from federal taxable income.
Both were valuable.
The larger lesson is that disability insurance should be evaluated based on the income it can actually provide, the circumstances under which it pays, and how long that protection can last.
For Idaho professionals whose households depend on their ability to work, understanding those details before a disability occurs can make an important difference.
Frequently Asked Questions About Disability Insurance Taxes in Idaho
1. Is employer-paid disability insurance taxable in Idaho?
Yes, employer-paid disability insurance benefits are generally subject to federal income tax when the employer pays the premiums and those premiums are excluded from the employee’s taxable income.
For example, if your employer provides long-term disability insurance at no cost to you, the benefits you receive after a qualifying disability will generally be taxable.
However, the tax treatment depends on how the premiums were funded and reported. Idaho residents should also confirm any applicable state income-tax obligations with a qualified tax professional.
2. Are individual disability insurance benefits tax-free?
Individual disability insurance benefits are generally excluded from federal taxable income when the policyholder pays the entire premium using after-tax dollars.
For example, an Idaho Falls professional who purchases a personal disability insurance policy with after-tax income may receive qualifying disability benefits without owing federal income tax on those payments.
However, individually owned policies are not automatically tax-free. Premium funding arrangements and other tax considerations can affect the outcome.
3. Can I have group and individual disability insurance at the same time?
Yes. You can have employer-sponsored group disability insurance and an individual disability insurance policy simultaneously.
Some Idaho professionals purchase individual disability coverage to supplement the protection available through their employers.
However, receiving benefits from both policies depends on each contract’s eligibility requirements, benefit limits, and provisions concerning other income or insurance benefits.
Before purchasing additional coverage, review how the policies coordinate and whether either insurer may reduce payments based on other benefits received.
4. Is disability insurance taxable if I pay premiums through payroll deductions?
It depends on whether your disability insurance premiums are deducted from your paycheck before or after taxes.
If premiums are paid through pre-tax payroll deductions, disability benefits are generally taxable. If you pay the entire premium using after-tax payroll deductions, benefits are generally excluded from federal taxable income.
Employees in Idaho Falls and Preston should ask their employer’s HR or payroll department whether disability insurance premiums are deducted on a pre-tax or after-tax basis.
That distinction can significantly affect the amount of disability income available after taxes.
5. Can I purchase individual disability insurance if I already have coverage through work?
Yes. Having disability insurance through your employer generally does not prevent you from applying for an individual disability income insurance policy.
Individual coverage may help supplement employer-sponsored benefits, depending on your income, occupation, existing coverage, health history, and the insurer’s underwriting requirements.
For healthcare professionals, business owners, and self-employed individuals in Idaho Falls, additional coverage may be worth evaluating when employer-sponsored benefits would not adequately replace their income.
Eagle Cap Insurance helps Idaho residents review existing disability policies, understand coverage limitations, and explore individual disability insurance options that may complement workplace benefits.
Learn more about Disability Insurance at Eagle Cap Insurance.
Tax information is provided for general educational purposes. Consult a qualified tax professional regarding your specific federal and Idaho income-tax obligations.
Review Your Disability Insurance With Eagle Cap Insurance
Whether you have disability insurance through your employer, own an individual policy, or are exploring coverage for the first time, Eagle Cap Insurance can help you better understand your options.
Kyle Bennett works with individuals and business owners to evaluate income protection and make informed insurance decisions.
Schedule a conversation with Kyle Bennett:
Book an Appointment With Eagle Cap Insurance
Call Eagle Cap Insurance: 208-529-1522
Learn More: Disability Insurance in Idaho
Official Sources
- Internal Revenue Service: Are Long-Term Disability Benefits Taxable?
- IRS Publication 525: Taxable and Nontaxable Income
- IRS Publication 15-B: Employer’s Tax Guide to Fringe Benefits
- Idaho Department of Insurance: Disability Insurance
- U.S. Bureau of Labor Statistics: Employee Benefits in the United States
- State of Idaho Office of Group Insurance: Disability Coverage
Disclaimer: This article is for general educational purposes and does not constitute individualized insurance, tax, financial, or legal advice. Disability insurance eligibility, benefits, exclusions, limitations, coordination provisions, and payment periods depend on the applicable insurance contract. Federal and Idaho income-tax treatment may vary based on premium funding, payroll arrangements, and individual circumstances. Consult a qualified tax professional regarding the tax treatment of disability insurance benefits.